- Knowledge Sharing
- September 15, 2026
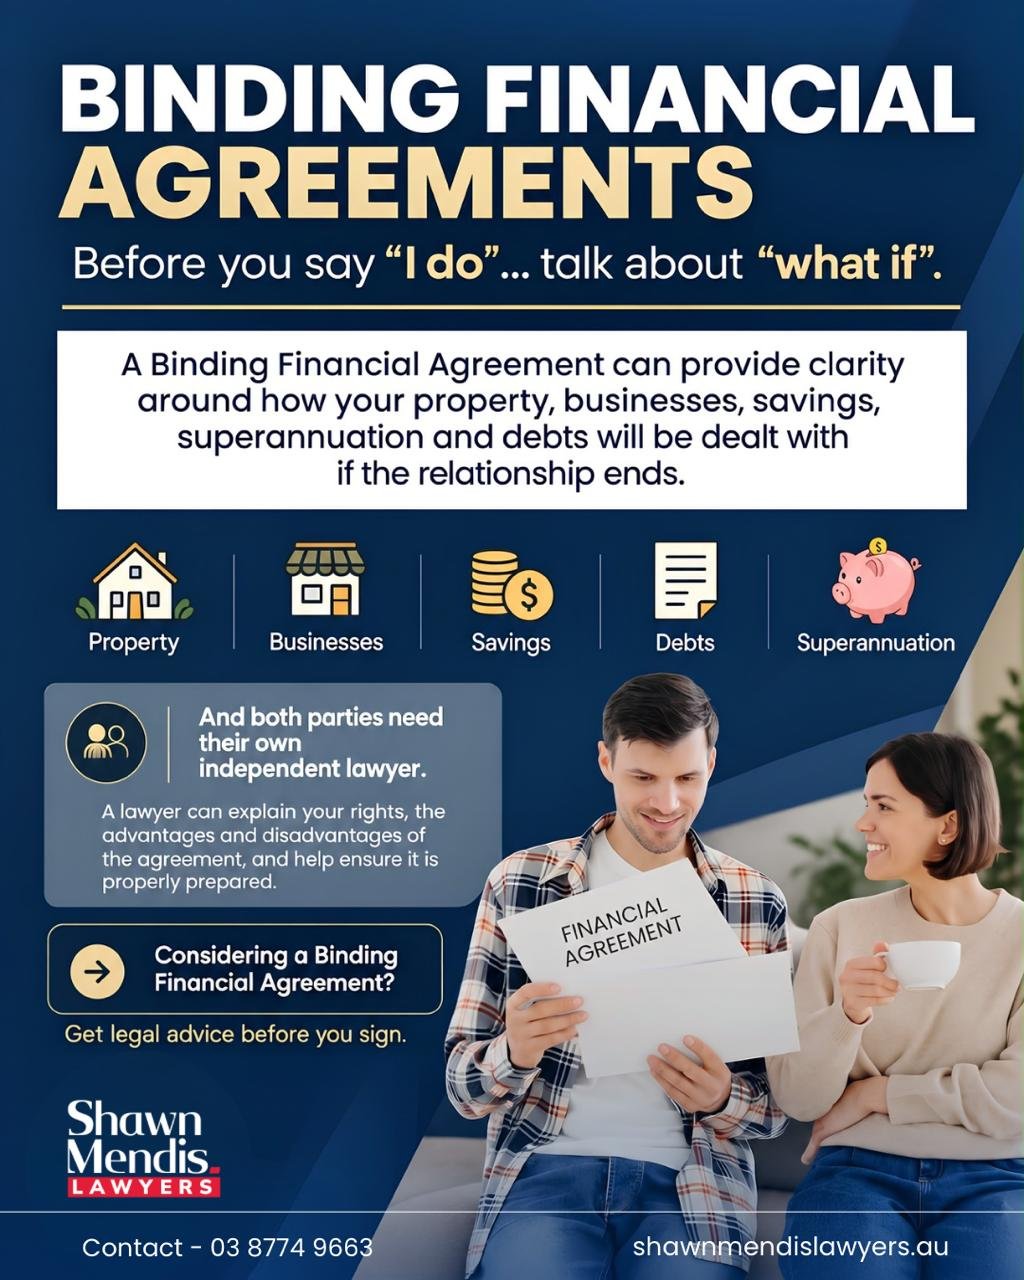
What is a Binding Financial Agreement?
Most people enter a relationship hoping it will last. However, sensible financial planning does not mean that you expect the relationship to fail.
It means that both people understand their financial position and agree on what should happen if their circumstances change.
A Binding Financial Agreement is a private legal agreement made under the Family Law Act 1975.
It may record how property, money, businesses, investments, superannuation and debts will be dealt with if a marriage or de facto relationship ends.
Many people call it a prenuptial agreement or prenup. However, financial agreements can be made before, during or after a marriage or de facto relationship.
When prepared carefully, a financial agreement can provide greater certainty, protect particular assets and reduce the risk of an expensive property dispute.
Who should consider a financial agreement?
A financial agreement is not only for wealthy people.
It may be worth considering where:
- You own a home or investment property.
- You operate a business.
- You have significant savings, shares or superannuation.
- You expect to receive an inheritance.
- You have children from an earlier relationship.
- You have been married or in a de facto relationship before.
- One person is entering the relationship with significantly more property.
- One person has substantial personal or business debts.
- Parents or family members have contributed money towards a property.
- You want to protect a family business, farm or trust interest.
- You and your partner want certainty about your financial arrangements.
A financial agreement may also help couples with similar financial positions who want to avoid uncertainty if their relationship ends.
When can a financial agreement be made?
Before marriage
An agreement made before marriage is commonly called a prenup.
It can record what each person owns before the marriage and what should happen to those assets if the marriage ends.
The agreement should be discussed and prepared well before the wedding.
Leaving it until a few days before the wedding may create concerns about pressure, influence and whether each person had enough time to obtain proper advice.
During marriage
Married couples may enter into a financial agreement during their marriage.
This may be appropriate where:
- One person receives an inheritance.
- A family contributes money towards a property.
- One person starts or purchases a business.
- The couple restructures their assets.
- Their financial circumstances change significantly.
- The parties want greater certainty about the future.
After separation or divorce
Separating couples may use a financial agreement to finalise their property and financial matters.
However, a financial agreement is not always the best option after separation. Consent orders may be more appropriate in some cases.
Your lawyer should explain both options and advise which one is better suited to your circumstances.
For de facto relationships
Financial agreements can also be made before, during or after a de facto relationship.
If a couple later marries, an earlier de facto financial agreement may cease to be binding. A new agreement may be required before or during the marriage.
It is important to obtain advice if your relationship status changes.
What can a financial agreement cover?
A financial agreement may deal with:
- The family home.
- Investment properties.
- Savings and bank accounts.
- Shares and other investments.
- Businesses and company interests.
- Trust interests.
- Superannuation.
- Motor vehicles and valuable personal property.
- Mortgages, credit cards and other debts.
- Property acquired during the relationship.
- Future inheritances.
- Financial contributions made by parents or family members.
- Financial support between the parties in certain circumstances.
- What happens if the parties separate.
The agreement should be prepared for your particular circumstances.
A standard online template may not properly deal with your assets, debts, family circumstances or the strict requirements of Australian family law.
Why does each person need a separate lawyer?
Each person must receive independent legal advice before signing a financial agreement.
This is not simply a recommendation made by lawyers. It is a statutory requirement under the Family Law Act 1975.
For married couples, section 90G requires each spouse to receive independent legal advice before signing.
For de facto couples, section 90UJ contains a similar requirement.
The advice must cover:
- The effect of the agreement on that person’s legal rights.
- The advantages of entering into the agreement.
- The disadvantages of entering into the agreement.
The lawyer must also provide a signed statement confirming that the required advice was given.
The legal advice must be independent. This means each person needs a different lawyer who is acting only in that person’s interests.
Why can one lawyer not advise both people?
One lawyer cannot properly provide independent advice to both parties because the parties may have different or competing interests.
For example, a term that protects one person’s business may significantly reduce the other person’s future property rights.
A term that benefits one party may be a disadvantage to the other.
A lawyer advising the first party may recommend that the agreement protect a particular property, business or inheritance. A lawyer advising the second party may recommend that the same clause be changed or removed.
The one lawyer cannot provide loyal and independent advice to both people about the same competing interests.
Can both people sign a conflict waiver and use the same lawyer?
No.
A conflict waiver cannot replace the statutory requirement for independent legal advice.
In some legal matters, clients may be able to give informed consent to a lawyer acting despite a potential conflict. However, financial agreements are different because the Family Law Act expressly requires each party to receive independent advice.
The parties cannot agree to ignore or waive a requirement imposed by legislation.
Even if both people sign a document stating that they accept the conflict, that does not make the advice independent and does not satisfy the purpose of sections 90G or 90UJ.
A conflict waiver cannot change the Family Law Act.
Using one lawyer for both parties may place the agreement at serious risk. It may also leave one or both parties without the independent advice required by law.
Each party must therefore have their own lawyer.
Why can the second lawyer not simply witness the signature?
We sometimes receive requests from clients who say:
“My partner’s lawyer prepared the agreement. Everything is already agreed. I only need you to witness my signature.”
Unfortunately, that is not sufficient.
If only a witnessed signature were required, you could attend a Justice of the Peace or another authorised witness.
The law requires independent legal advice because signing a financial agreement may remove or significantly change rights you would otherwise have under the Family Law Act.
By signing, you may be agreeing that:
- You cannot make a future claim against certain property.
- You will receive less than you might otherwise receive under family law.
- A business, home or investment will remain entirely with the other person.
- You will be responsible for particular debts.
- You will not make a claim against a future inheritance.
- Particular financial support will be limited or excluded.
The lawyer must read the complete agreement, understand your financial position, identify the legal consequences and explain the advantages and disadvantages.
The lawyer cannot responsibly sign the legal advice certificate without completing that work.
Is a financial agreement automatically binding?
No.
Calling a document a “Binding Financial Agreement” does not automatically make it binding.
The agreement must satisfy strict legal requirements.
Generally:
- The agreement must be in writing.
- It must be signed by all parties.
- Each person must receive independent legal advice before signing.
- The advice must cover the effect, advantages and disadvantages of the agreement.
- Each person must receive a signed statement from their lawyer confirming that the advice was given.
- The required legal advice statements must be exchanged.
- The agreement must not have been terminated.
- The agreement must not have been set aside by a court.
The law governing financial agreements is technical. A mistake in the drafting, legal advice, disclosure or signing process may cause a major dispute later.
What are the chances of a financial agreement being set aside?
There is no reliable percentage that can be given.
Anyone who says that a financial agreement is guaranteed to be binding or has a fixed percentage chance of surviving a challenge is not giving a realistic answer.
The chance of an agreement being set aside depends on:
- How it was prepared.
- Whether the correct section of the Family Law Act was used.
- Whether both parties made proper financial disclosure.
- Whether each party received genuinely independent legal advice.
- Whether the lawyers explained the advantages and disadvantages properly.
- Whether both people had enough time to consider the agreement.
- Whether either person was pressured into signing.
- Whether there was fraud, duress, undue influence or unconscionable conduct.
- Whether the wording is clear and can be carried out.
- Whether important circumstances later changed.
- Whether children and future hardship were properly considered.
- Whether the document was signed and exchanged correctly.
A carefully drafted agreement supported by full disclosure, separate legal advice, reasonable negotiation and a proper signing process has a stronger chance of being upheld.
An agreement prepared at the last minute, with incomplete disclosure, unequal bargaining power or pressure to sign carries a much higher risk of challenge.
Does an unfair agreement automatically get set aside?
Not necessarily.
A financial agreement is not automatically invalid simply because one person later believes it was unfair.
However, a seriously one sided outcome may become relevant when considered together with other circumstances such as pressure, vulnerability, lack of time, inadequate advice or unconscionable conduct.
The court examines the complete circumstances surrounding the agreement.
The High Court decision in Thorne v Kennedy is an important example. The agreements were signed shortly before and after the wedding. The woman was in a vulnerable position, had substantially fewer assets and was told the wedding would not proceed unless she signed.
The High Court found that the agreements should be set aside because of undue influence and unconscionable conduct.
This does not mean every unequal agreement will be set aside. It shows why proper timing, genuine choice and independent advice are critical.
When can a court set aside a financial agreement?
For marriages, section 90K of the Family Law Act sets out circumstances in which a court may set aside an agreement.
For de facto relationships, similar grounds appear in section 90UM.
These circumstances may include:
- Fraud.
- Failure to disclose an important financial matter.
- An agreement entered into to defeat or prejudice a creditor.
- An agreement that is void, voidable or unenforceable.
- An agreement that cannot practically be carried out.
- Unconscionable conduct.
- Serious pressure or undue influence.
- A material change concerning the care, welfare or development of a child where enforcing the agreement would cause hardship.
- Improper conduct involving a superannuation interest.
The person seeking to set aside the agreement must apply to the court and establish an available legal ground.
Merely regretting the agreement or disliking the outcome is not usually enough.
What makes an agreement stronger?
No lawyer can guarantee that an agreement will never be challenged. However, the risk can be reduced through a careful process.
A stronger agreement will generally involve:
- Early discussions without last minute pressure.
- Separate and genuinely independent lawyers.
- Complete financial disclosure from both parties.
- Clear identification and valuation of assets and debts.
- Proper consideration of businesses, trusts and superannuation.
- Careful drafting suited to the parties’ circumstances.
- Clear advice about advantages and disadvantages.
- Enough time for each person to consider the advice.
- Genuine negotiation where changes are required.
- Clear evidence that both parties signed voluntarily.
- Properly signed and exchanged legal advice statements.
- Review when significant circumstances change.
What increases the risk of an agreement being set aside?
The risk may be higher where:
- The agreement was presented shortly before a wedding.
- One party was told that the wedding or relationship would end unless they signed.
- One party had limited English and no independent interpreter.
- Important assets or debts were not disclosed.
- One party did not receive proper independent advice.
- The same lawyer attempted to advise both parties.
- A lawyer merely witnessed a signature without giving proper advice.
- The agreement was copied from an online template.
- The agreement uses unclear or inconsistent terms.
- Handwritten changes were made after legal advice.
- One party was vulnerable or financially dependent.
- The agreement cannot practically be carried out.
- Significant changes affecting children were not considered.
- The parties later married but relied on an earlier de facto agreement.
Full financial disclosure is essential
Both parties should provide complete and accurate information about their financial circumstances.
This may include:
- Property.
- Bank accounts.
- Shares and investments.
- Businesses.
- Companies and trusts.
- Superannuation.
- Income.
- Personal loans.
- Mortgages.
- Credit card debts.
- Tax liabilities.
- Other significant financial resources.
Failing to disclose an important asset or liability may place the agreement at risk.
Your lawyer cannot provide meaningful advice without understanding your complete financial position and the financial position disclosed by the other party.
Do not leave the agreement until the last minute
A financial agreement should not be prepared and signed immediately before a wedding.
Both parties need reasonable time to:
- Consider the proposed terms.
- Provide financial disclosure.
- Obtain separate legal advice.
- Ask questions.
- Request changes.
- Consider the advantages and disadvantages.
- Make a free and informed decision.
Last minute pressure can create unnecessary stress and increase the risk of a future challenge.
If you are planning to marry, speak with your lawyer as early as possible.
What is the difference between a financial agreement and consent orders?
After separation, property arrangements can often be documented by a financial agreement or consent orders.
Financial agreement
A financial agreement is a private contract between the parties.
Each person must receive independent legal advice.
The agreement is not automatically reviewed or approved by the court when it is signed.
Consent orders
Consent orders are submitted to the Federal Circuit and Family Court of Australia for approval.
The court must be satisfied that the proposed property orders are just and equitable before making them.
Consent orders may provide greater certainty in some cases. A financial agreement may be more suitable in others.
The best option depends on your assets, liabilities, relationship circumstances and the proposed terms.
Should a financial agreement be reviewed later?
A financial agreement should be reviewed when significant circumstances change.
For example:
- You marry after living in a de facto relationship.
- You have children.
- You purchase a home together.
- One person receives a substantial inheritance.
- A new business is established.
- One person stops working to care for children.
- Your financial positions change significantly.
- You move overseas.
- The agreement no longer reflects your intentions.
A financial agreement does not automatically update itself when your life changes.
Do not make informal or handwritten changes. Obtain legal advice about whether a new agreement or termination agreement is required.
How can Shawn Mendis Lawyers assist?
Shawn Mendis Lawyers can assist with financial agreements made:
- Before marriage.
- During marriage.
- After separation or divorce.
- Before a de facto relationship.
- During a de facto relationship.
- After a de facto relationship ends.
We can assist by:
- Understanding your financial circumstances and objectives.
- Explaining your rights in clear and simple language.
- Preparing an agreement suited to your circumstances.
- Reviewing an agreement prepared by your partner’s lawyer.
- Advising you about the advantages and disadvantages.
- Negotiating appropriate amendments.
- Ensuring the signing process is completed correctly.
- Advising whether consent orders may be a better option after separation.
A financial agreement can have lifelong financial consequences.
Do not sign until you fully understand how it affects your legal and financial future.
Contact Shawn Mendis Lawyers to arrange a confidential family law consultation.
Important information
This article provides general information only. It is not legal or financial advice.
Financial agreements are complex. No lawyer can guarantee that an agreement will never be challenged or set aside.
The strength of an agreement will depend on its terms, the circumstances in which it was prepared and signed, the financial disclosure made and the quality of the independent legal advice received by each party.